
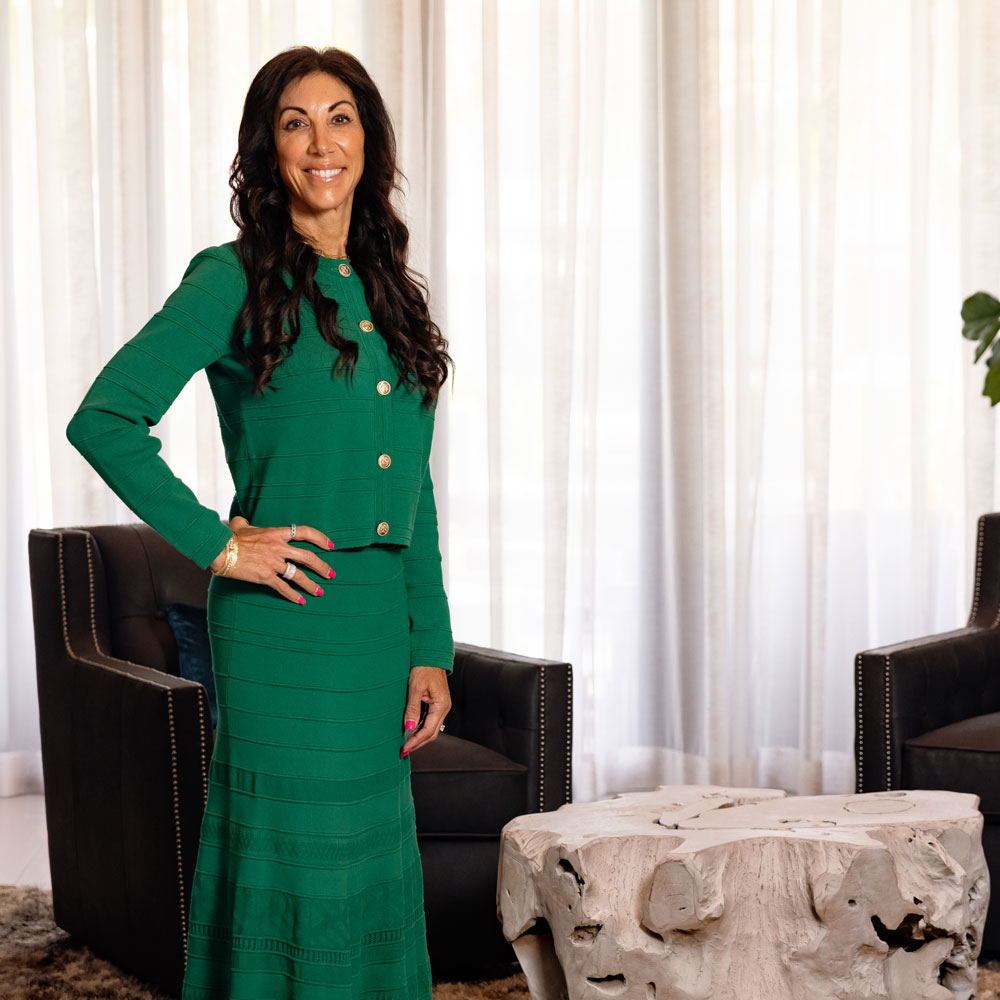
Elizabeth M. Bennett, MBA
Principal and Certified Financial Planner
Intercoastal Wealth Planning
The second half of the year is a good time to review your required minimum distribution (RMD) if you have not already taken it. If you are charitably inclined, a qualifi ed charitable distribution (QCD) may help satisfy all or part of your RMD while supporting a cause you care about.
A QCD is transferred directly from your IRA to an eligible charity. For 2026, IRA owners age 70½ or older may make QCDs of up to $111,000. The eligible amount is generally excluded from taxable income, although it cannot also be claimed as a charitable deduction. “Historically, the fourth quarter has often been positive, so it may be a good time to consider taking and distributing that money,” says Bennett. Your decision, however, should refl ect your personal plan rather than market expectations alone.
As the “Season of Giving” approaches, individuals may also give up to $19,000 per recipient in 2026 under the federal annual gift-tax exclusion. Married couples may give up to $38,000 per recipient when the gifts are properly structured. Gifts above those amounts may require a gift-tax return, but they do not necessarily create an immediate tax. Personal gifts are not income-tax deductible for the donor.
Giving is also an important reason to review your estate plan. Confirm that beneficiary designations, trusts, and charitable intentions reflect your wishes.
“If you are considering a gift, work with your financial advisor and tax professional to understand how it fi ts into your overall financial plan,” Bennett emphasizes.
INTERCOASTAL WEALTH PLANNING
561-210-7339
intercoastalwealth.com